Ind AS Transitions
First-time Ind AS adoption, managed end to end.
The problem we solve
Ind AS can change your reported profit, net worth and ratios.
Ind AS conversion alters reported profits and net worth
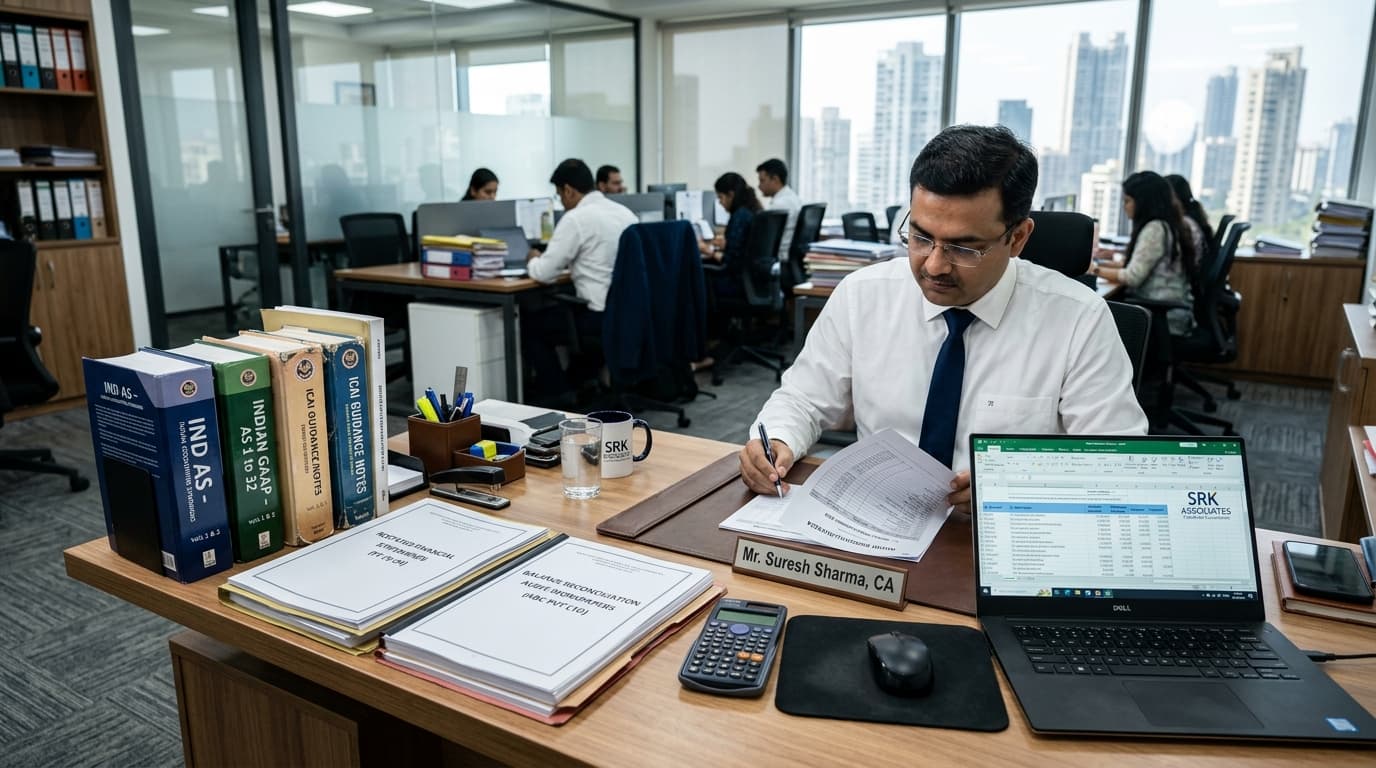
Moving from Indian GAAP to Ind AS is not just a reporting exercise. It can change reported profits, net worth, key ratios and loan covenants. Companies make this move when they cross the applicability thresholds, prepare for a main-board listing, or become part of a group that reports under Ind AS. Many underestimate how much effort it takes.
The main difficulties sit in judgement-heavy standards: revenue recognition, financial instruments and expected credit losses, leases, fair valuation, business combinations and deferred tax. On top of these, the first-time adoption choices under Ind AS 101 affect results for years afterwards. Data that was never collected under Indian GAAP has to be rebuilt, and auditors have to sign off on every judgement.
End-to-end conversion with zero audit surprises
We manage the conversion end to end, so the first Ind AS financial statements are accurate, defensible and on time.
The result is a smooth, well-documented transition with no audit surprises, and stakeholders who understand what changed and why.
How the engagement runs
A structured, milestone-driven roadmap, run by the same partner-led team from the first diagnostic to the delivered outcome.
- 01
Impact assessment
We identify the differences between Indian GAAP and Ind AS that apply to your business and estimate their effect on profit, equity, ratios and covenants.
- 02
First-time adoption choices
We evaluate the optional exemptions and mandatory exceptions under Ind AS 101 and recommend the choices that best suit the company.
- 03
Accounting policies and position papers
We draft Ind AS-compliant policies and technical papers on the key judgements, agreed in advance with your auditors.
- 04
Conversion and reconciliations
We prepare the opening Ind AS balance sheet, the restated comparatives and the reconciliations required, along with the supporting computations for ECL, fair value, leases and deferred tax.
- 05
Embedding and training
We update chart of accounts, systems and closing processes, and train finance teams, so ongoing Ind AS reporting is business as usual.
Work products built to withstand scrutiny
Every work product is prepared to the standard expected by regulators, boards, and institutional capital providers.
- 01Ind AS gap diagnostic and balance sheet impact assessment
- 02Technical accounting position papers on key standards and judgements
- 03Ind AS 101 first-time adoption exemptions and exceptions roadmap
- 04Opening Ind AS balance sheet and GAAP reconciliation statements
- 05Chart of accounts mapping, accounting policy manual, and team training
Two commitments that shape this engagement
Regulatory Depth
Mastery across capital market regulations, accounting standards, Companies Act, and exchange governance frameworks, engineered directly into every transaction from initiation.
Scale with Discipline
Every engagement is designed to institutionalize your financial architecture, building permanent reporting rigor, internal controls, and investor confidence as your enterprise grows.
Related service lines
Clients running this mandate frequently pair it with these disciplines.
 Finance Function
Internal Financial Controls
A controls framework built to operate, not merely exist as a document.
Explore service Capital Markets
SME to Main Board Migration
Move to the NSE or BSE Main Board with reporting and governance that clear review.
Explore service Capital Markets
End-to-End IPO & Growth Advisory
From IPO readiness to listing and beyond, with one partner-led team throughout.
Explore serviceMoving to Ind AS? Chat with us.
Speak directly with a Partner. We will shape the right engagement for your scale and timeline.